
How Much Money You Can Gift Without Being Taxed

Did you know you can give a family member, friend, or even a stranger money each year without paying taxes on the gifted amount? For 2026, the IRS lets you give up to $19,000 per recipient each year without filing anything. The IRS adjusts it periodically for inflation, and it increased the amount to $20,000 for 2027.
There is also a second, much larger allowance most people don’t know about. It’s called the lifetime exclusion, and it can make a huge difference when you want to help someone buy a home.
A few years ago I recorded a video explaining these tax rules. The numbers have changed since then, but the idea behind them stays the same, so feel free to check it out.
What Is the Lifetime Exclusion?
For 2026, the federal lifetime exclusion is $15,000,000. That is the total amount you can give during your life, above the annual limit, before gift or estate taxes could apply. For estates of people who die in 2027, the amount rises to $15,480,000.
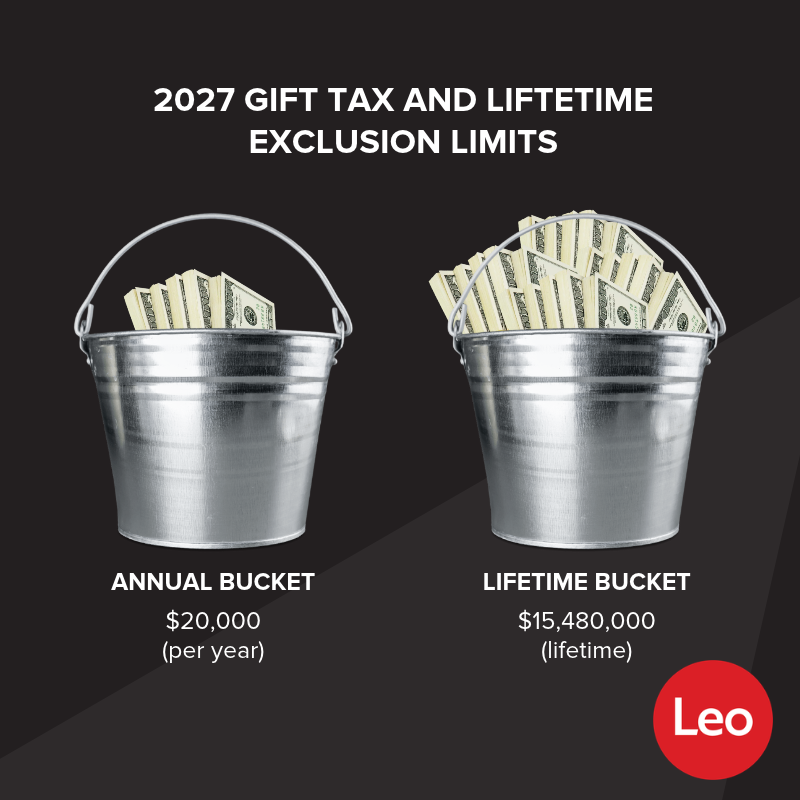
Think of your gifting as two buckets:
- The annual bucket ($19,000 in 2026, $20,000 in 2027) refills every calendar year.
- The lifetime bucket ($15,000,000 in 2026, $15,480,000 in 2027) does not refill. Each dollar you use reduces what’s left, though the total itself is indexed for inflation over time.
Here’s an example. Say you give your daughter $119,000 in 2026. The first $19,000 comes from your annual bucket, and the remaining $100,000 comes from your lifetime bucket. Your lifetime exclusion drops from $15,000,000 to $14,900,000. You don’t owe any taxes on that gifted amount, but you do need to file a gift tax return (IRS Form 709) to report the gift.
Why It Matters for Estate Planning
The lifetime exclusion also affects estate taxes. Estate tax applies only when the value of what you leave behind exceeds your remaining lifetime exclusion, and the rate on the excess can be between 18% and 40%. Each dollar you give during your life from the lifetime bucket reduces the amount that can pass tax-free at your death. For most families, the exclusion is high enough that an estate tax never comes up. Still, it’s worth knowing the numbers.
Married couples can combine their exclusions. For estates of spouses who die in 2026, each has a $15,000,000 exclusion. in other words, a couple can shelter about $30,000,000 in total. For 2027 deaths, the figure rises to $15,480,000 per person, or $30,960,000 for a legally married couple.
Key Rules to Know
- No relationship required. You can give to anyone, related or not.
- The recipient doesn’t owe tax on monetary gifts they receive.
- Give from the right person. Each giver should write a separate check. If Mom and Dad each give $19,000, you need two checks, one from each of them, not a combined check of $38,000.
- File when required. Gifts within the annual limit generally don’t need to be reported. Gifts above the limit require a Form 709, even though no tax is usually due.
- Keep your wealth team in the loop. Let us know if you want to gift money, especially for real estate purchases. If you’re gifting money for a home purchase, mortgage underwriting may need to verify where the money came from. A gift letter and proper documentation can keep your loan on track. Let’s talk through the details before any money changes hands.
Everyone’s situation is different, so think of this as a starting point rather than tax or legal advice. For questions about your own plans, a CPA or estate attorney is the best person to talk with.